Sports Streaming Services And Technology Market (2026 – 2033)
Sports Streaming Services And Technology Market Summary
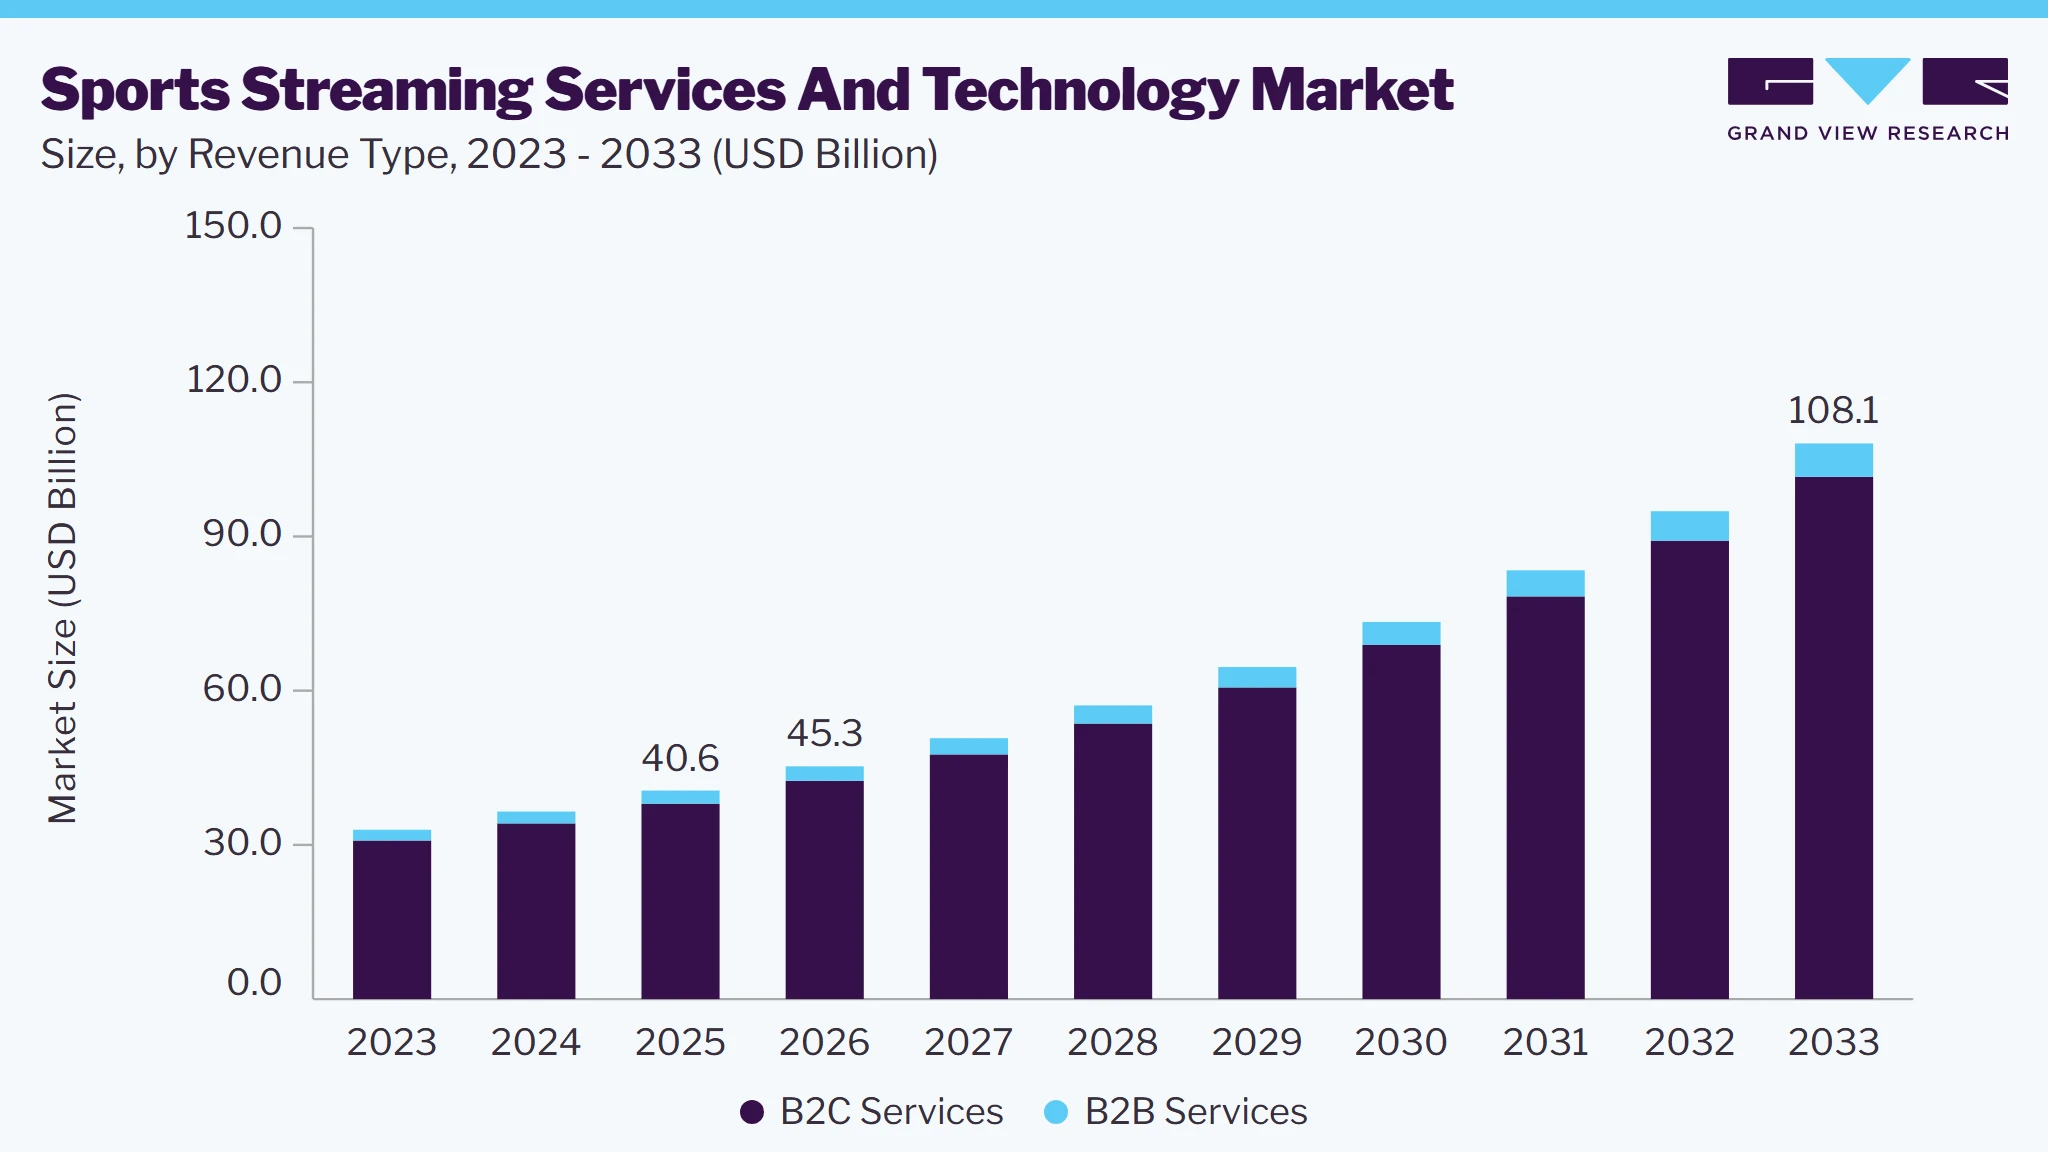
The global sports streaming services and technology market size was valued at USD 40.6 billion in 2025 and is projected to grow from USD 45.3 billion in 2026 to USD 108.1 billion by 2033, at a CAGR of 13.2% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 35.1% in 2025. Market growth is primarily driven by the rising adoption of over-the-top (OTT) streaming platforms, increasing consumption of live sports content on digital devices, growing demand for personalized and interactive viewing experiences, and the expanding 5G and high-speed internet infrastructure.
Key Market Trends & Insights
- By revenue type: B2C services segment accounted for the largest revenue share of over 93.0% in 2025.
- By sport type: Football/soccer segment led the market with a share of over 36.0% in 2025.
Regional Highlights
- Largest regional market: North America (35.1% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By Country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 40.6 Billion
- Estimated market size in 2026: USD 45.3 Billion
- Projected market size by 2033: USD 108.1 Billion
- CAGR (2026-2033): 13.2%
Request a free sample copy or view report summary: https://www.grandviewresearch.com/industry-analysis/sports-streaming-services-technology-market-report/request/rs1
Sports organizations, broadcasters, leagues, and technology providers are increasingly leveraging AI-driven content recommendations, cloud-native broadcasting, adaptive bitrate streaming, real-time analytics, and multi-camera viewing capabilities to enhance audience engagement and maximize monetization opportunities. Furthermore, the expansion of 5G networks, edge computing, and cloud-based production workflows is enabling high-quality, ultra-low-latency streaming while reducing infrastructure costs and improving scalability.
Additionally, media companies and sports rights holders remain the primary growth drivers of the global sports streaming services & technology market through sustained investments in premium sports broadcasting rights and direct-to-consumer (D2C) streaming platforms. Leading sports leagues increasingly prioritize digital distribution to expand global reach and diversify revenue streams beyond traditional television, thereby supporting the expansion of the Sports streaming services & technology industry.
Market Dynamics
The sports streaming services & technology industry is shaped by a rapid shift from traditional linear television to over-the-top (OTT) sports streaming platforms, increasing internet and smartphone penetration, and growing consumer demand for anytime, anywhere access to live sporting events. Rising investments by streaming providers in exclusive digital broadcasting rights, coupled with advancements in cloud-based video delivery, artificial intelligence (AI), and ultra-low-latency streaming technologies, are transforming the sports media landscape.
Market Concentration & Characteristics
The global sports streaming services & technology market is moderately concentrated, with major broadcasters, OTT platforms, technology providers, cloud companies, and sports-rights holders maintaining strong market positions through exclusive content rights, large subscriber bases, global distribution networks, scalable cloud infrastructure, and integrated streaming ecosystems. However, the technology and platform landscape remains partly fragmented, with regional platforms, niche sports services, white-label OTT providers, and specialized vendors competing in areas such as live production, CDN delivery, personalization, analytics, advertising technology, and content management. The market demonstrates a high degree of innovation, driven by AI-powered recommendations and highlights, cloud-native streaming, low-latency delivery, 5G, multi-CDN architecture, interactive viewing, AR/VR, dynamic ad insertion, and real-time sports data. M&A and strategic partnership activity is also evident as broadcasters, leagues, technology companies, and streaming platforms seek to strengthen sports-rights portfolios, direct-to-consumer capabilities, content distribution, and fan-engagement technologies.
Revenue Type Insights
The B2C services segment accounted for the largest market share of over 93.0%, in 2025, driven by the shift from traditional TV towards OTT and direct-to-consumer viewing, increasing smartphone, connected-TV, broadband, and 5G penetration, rising demand for flexible access to live and on-demand sports content, expansion of exclusive league and tournament rights, and the growing adoption of SVOD, PPV, AVOD, and hybrid pricing models. Growth is further supported by AI-powered personalization, localized content, interactive viewing, real-time statistics, fantasy and betting integrations, social engagement, and multi-device accessibility, which improve fan engagement and support subscriber acquisition and retention.
Regional Insights
North America dominated the sports streaming services & technology market, with a share of 35.1% in 2025, driven by high digital adoption, widespread connected TV (CTV) penetration, and strong consumer willingness to pay for premium sports content. The region is witnessing increased investment in AI-powered personalization, dynamic ad insertion, cloud-based production, and low-latency streaming to enhance viewer engagement and monetize live sports. Rights holders and streaming platforms are also focusing on bundled offerings, interactive viewing experiences, and data-driven fan engagement.
Sports Streaming Services And Technology Market Report Scope
|
Report Attribute |
Details |
|
Market size in 2025 |
USD 40.6 billion |
|
Estimated market size in 2026 |
USD 45.3 billion |
|
Projected market size by 2033 |
USD 108.1 billion |
|
Growth rate |
CAGR of 13.2% from 2026 to 2033 |
|
Base year of estimation |
2025 |
|
Actual data |
2021 – 2024 |
|
Forecast period |
2026 – 2033 |
|
Quantitative units |
Revenue in USD million/billion and CAGR from 2026 to 2033 |
|
Report coverage |
Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
|
Segments covered |
Revenue type, sport type, region |
|
Regional scope |
North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
|
Country scope |
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Taiwan; Brazil; UAE; Saudi Arabia; South Africa |
|
Key companies profiled |
ESPN Enterprises, Inc.; DAZN Limited; YouTube TV; FuboTV Inc.; Star India Private Limited; NBCUniversal Media, LLC. (Peacock TV LLC); Paramount; Sky UK Limited; beIN MEDIA GROUP; Sony Pictures Networks India Private Limited; Amazon.com, Inc.; Akamai Technologies; Amazon Web Services, Inc.; Brightcove Inc.; MediaKind; Harmonic Inc.; Synamedia Ltd.; Deltatre S.p.A.; Endeavor Streaming, LLC; ViewLift, Inc.; Amagi Media Labs Private Limited; Globecast; Encompass Digital Media. |
|
Customization scope |
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope. |
|
Pricing and purchase options |
Avail customized purchase options to meet your exact research needs. Explore purchase options |